The 2026 Medicare Part B Hike Is Already Hitting Your Social Security Check
2026 Medicare Part B costs went up — and if you’re on Social Security, you’ve likely already felt it.
Here’s a quick summary of what changed this year:
| Cost | 2025 | 2026 | Change |
|---|---|---|---|
| Standard monthly premium | $185.00 | $202.90 | +$17.90 |
| Annual deductible | $257.00 | $283.00 | +$26.00 |
| Lowest IRMAA premium | $259.00 | $284.10 | +$25.10 |
| Highest IRMAA premium | $628.90 | $689.90 | +$61.00 |
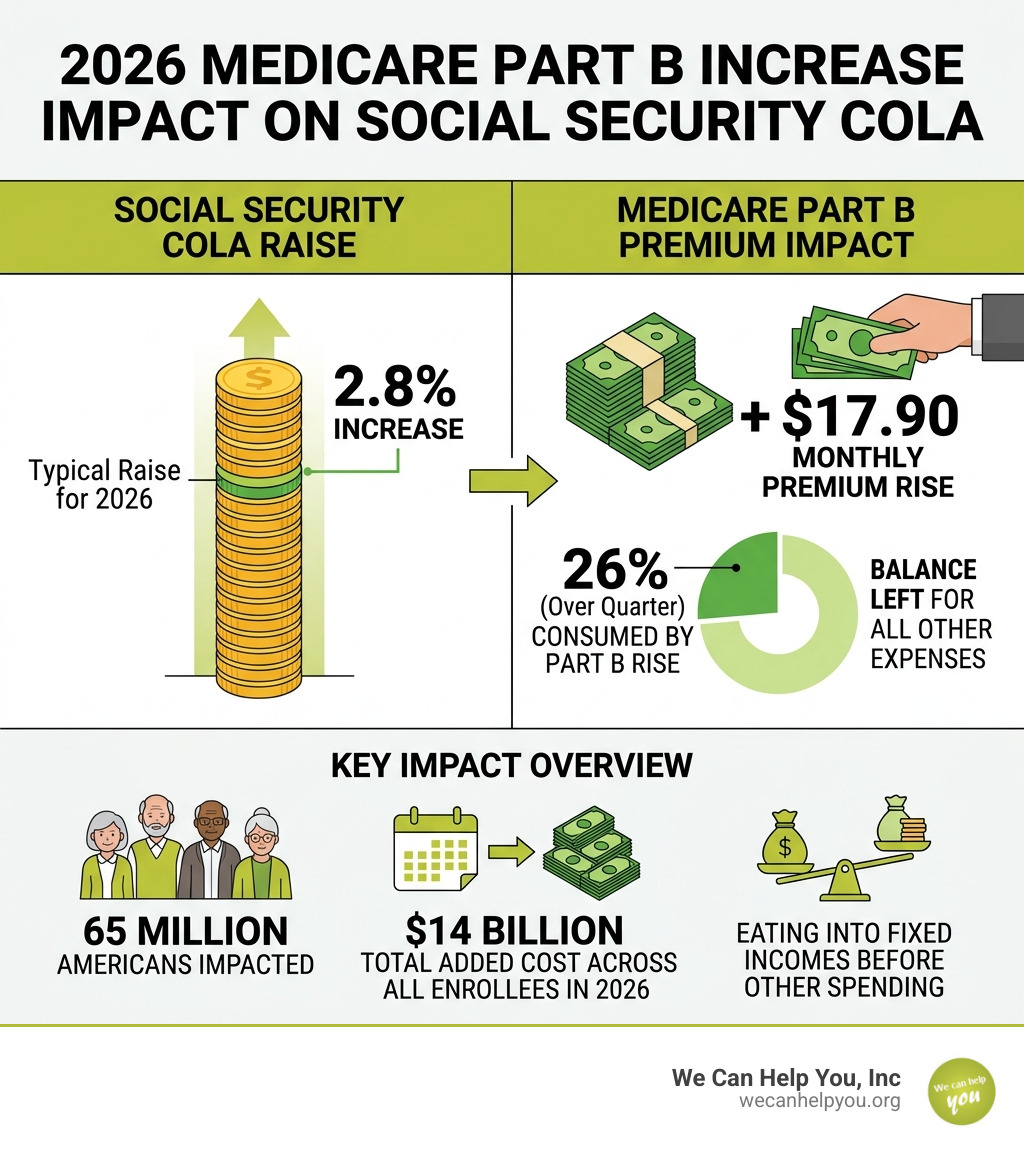
For most people, that $17.90 monthly jump doesn’t sound catastrophic. But here’s the problem: Social Security’s 2026 cost-of-living adjustment (COLA) was only 2.8%. The Part B premium increase alone swallowed more than a quarter of that raise before you spent a single dollar on food, rent, or gas.
For the roughly 65 million Americans enrolled in Medicare Part B, the total added cost across all enrollees is $14 billion in 2026. And for those on fixed incomes, every dollar counts.
This guide breaks down exactly what changed, why it happened, and what you can do to protect your retirement income.
2026 Medicare Part B Premiums and Deductibles: The Official Numbers
When the Centers for Medicare & Medicaid Services (CMS) released the final figures for 2026, many of us in the retirement planning community took a deep breath. We knew an increase was coming, but seeing the official numbers in black and white makes it real. For the calendar year 2026, the standard monthly premium for 2026 Medicare Part B is $202.90.
This represents a monthly increase of $17.90 from the 2025 rate of $185.00. While a nearly $18 increase might seem manageable in isolation, it adds up to over $2,400 per year in premiums alone. Furthermore, the annual deductible—the amount you must pay out-of-pocket before Medicare starts covering its 80% share—has risen to $283.00, a $26 increase from the previous year.
It is important to understand that these figures are the baseline. Depending on your income and your specific health needs, your actual costs could be significantly higher. You can find a deep dive into these figures in our Medicare Premiums 2026 Complete Guide. For those who want to see the official government data, the 2026 Medicare Parts A & B Premiums and Deductibles | CMS fact sheet provides the regulatory breakdown.
Breaking Down the 2026 Medicare Part B Monthly Premium
The jump from $185.00 to $202.90 represents a 9.7% increase. To put that in perspective, inflation in many other sectors of the economy has started to cool, but healthcare continues to climb. Why such a sharp rise?
CMS calculates these premiums based on “actuarial rates.” Essentially, they look at the total projected cost of the Part B program—which covers doctor visits, outpatient hospital services, and medical equipment—and set the premium to cover approximately 25% of those costs. The remaining 75% is funded by the federal government’s general revenue. For 2026, the monthly actuarial rate for aged enrollees is $405.40. You can see how this compares to previous years by reviewing our Part B Premiums In 2025 The Monthly Breakdown.
The Impact of Skin Substitute Spending on 2026 Rates
Believe it or not, a specific category of medical supplies called “skin substitutes” played a major role in your 2026 premium calculation. In previous years, spending on these products—often used for chronic wound care—skyrocketed due to what regulators identified as significant waste and overpayment.
Under the 2026 Physician Fee Schedule Final Rule, CMS implemented aggressive cost-saving measures that are expected to drop spending on skin substitutes by 90% without hurting patient care. According to the Official 2026 Medicare Actuarial Notice, if these regulatory actions hadn’t been taken, your 2026 Medicare Part B premium would have been approximately $11.00 higher per month. While we are still seeing an increase, this “waste reduction” prevented the hike from being even more painful.
How the 2026 Medicare Part B Increase Erodes Social Security Benefits
The relationship between Medicare and Social Security is like a see-saw. When Medicare premiums go up, the net amount of your Social Security check goes down. This year, that see-saw is heavily tilted.
With a Social Security COLA of only 2.8%, many seniors were hoping for a bit of breathing room in their budgets. Instead, the $17.90 Part B increase is set to consume more than 25% of that cost-of-living adjustment for the average retiree. In fact, Part B premiums as a share of annual Social Security benefits will reach an all-time high of 9.4% in 2026.
We’ve discussed this trend in our article Will My Medicare Premiums Rise In 2026, and the reality is that the purchasing power of the average senior is being squeezed. When you factor in the Part B deductible and other out-of-pocket costs, the “real” value of your Social Security benefit is lower than it appears on your statement.
The Hold Harmless Provision in 2026
There is a bit of good news for some: the “Hold Harmless” provision. This is a federal law that prevents your Social Security check from decreasing from one year to the next due to an increase in Medicare Part B premiums.
If the $17.90 premium hike is larger than the dollar amount of your 2.8% COLA increase, the Hold Harmless provision may kick in to limit your premium increase, ensuring your net check stays at least the same as it was in 2025. However, this doesn’t apply to everyone. You aren’t protected by Hold Harmless if:
- You are new to Medicare in 2026.
- You pay an income-related adjustment (IRMAA).
- You are billed directly for Medicare (meaning it’s not deducted from a Social Security check).
If you’re looking for ways to manage these costs, check out our guide on Is It Possible To Reduce My Medicare Part B Premium.
Long-term Projections for Retiree Healthcare Costs
Looking ahead, the financial landscape for retirees remains challenging. Current data shows that after medical spending, the median beneficiary is left with only 71% of their Social Security income. For those in the 25th percentile (lower-income earners), that number drops to a staggering 52%.
This is why long-term planning is so critical. As we explore in Prepare For Tomorrow What To Expect For 2027 Medicare Costs, healthcare is often the single largest “wildcard” expense in retirement. Understanding the trajectory of 2026 Medicare Part B is just the first step in securing your financial future.
Understanding 2026 Medicare Part B IRMAA and Income Thresholds
If you are a higher earner, the $202.90 standard premium is only the starting point. About 8% of Medicare beneficiaries are required to pay an Income-Related Monthly Adjustment Amount, or IRMAA.
CMS uses your tax returns from two years prior to determine if you owe this surcharge. For your 2026 premium, they are looking at your 2024 Modified Adjusted Gross Income (MAGI). If your income exceeded certain thresholds, you’ll see an extra charge on your bill.
| Filing Status | 2024 MAGI Income Tier | Total 2026 Monthly Premium |
|---|---|---|
| Individual | $109,000 or less | $202.90 |
| Individual | $109,001 – $136,000 | $284.10 |
| Individual | $136,001 – $170,000 | $405.80 |
| Individual | $170,001 – $204,000 | $527.50 |
| Individual | $204,001 – $499,999 | $649.30 |
| Individual | $500,000 or more | $689.90 |
Note: Thresholds for joint filers start at $218,000.
You can find more details on how these surcharges are calculated in our article How Irmaa Surcharges In 2026 Impact High Earners.
Navigating 2026 Medicare Part B Surcharges for High Earners
The income brackets for 2026 have been adjusted slightly for inflation, with the base threshold for individuals rising to $109,000 (up from $103,000 in 2025). However, the cost of the surcharges themselves has also increased.
At the highest tier—for those with an income of $500,000 or more (individual) or $750,000 or more (joint)—the total monthly Part B premium is a whopping $689.90 per person. If you are a married couple in this bracket, you are looking at over $16,500 a year just for Part B coverage. For a deeper breakdown, see Decoding 2026 Irmaa Brackets What The Projections Mean For You.
Appealing an IRMAA Determination
What if your income in 2026 is much lower than it was in 2024? This is a common scenario for people who recently retired. You shouldn’t have to pay a surcharge based on a salary you no longer earn.
The Social Security Administration allows you to appeal an IRMAA determination if you have experienced a “Life-Changing Event” (LCE). Qualifying events include:
- Retirement (Work stoppage)
- Work reduction
- Divorce or annulment
- Death of a spouse
- Loss of income-producing property
To appeal, you’ll need to file Form SSA-44. We have more resources on this process under our Tag/Medicare Part B Irmaa/.
Beyond Part B: 2026 Medicare Part A and Coverage Updates
While 2026 Medicare Part B is the main focus for most, Part A (Hospital Insurance) is also seeing cost increases. Most people receive “premium-free” Part A because they worked and paid Medicare taxes for at least 10 years. However, the deductibles and coinsurance for hospital stays are going up:
- Part A Hospital Deductible: $1,736 per benefit period (up $60 from 2025).
- Daily Coinsurance (Days 61-90): $434 per day.
- Skilled Nursing Facility Coinsurance (Days 21-100): $217 per day.
For a full list of what is covered under these costs, visit the official What Part B covers | Medicare page.
Immunosuppressive Drug Coverage and Special Benefits
For certain individuals, Medicare offers specialized coverage. If you had a kidney transplant and your full Medicare coverage is ending (usually 36 months post-transplant), you may be eligible for the Part B Immunosuppressive Drug Benefit. For 2026, the standard premium for this limited coverage is $121.60.
Another major win for beneficiaries in 2026 is the continued protection for insulin costs. Under the Inflation Reduction Act, your out-of-pocket cost for a month’s supply of Part B-covered insulin (such as that used in a pump) is capped at $35, and the Part B deductible does not apply. You can learn more about these types of cost-saving “givebacks” in our Understanding Medicare Part B Giveback Offers guide.
Telehealth and Behavioral Health Expansions
2026 is a landmark year for Medicare coverage flexibility. Many of the telehealth rules that were temporary during the pandemic have been made permanent or extended. For instance, Medicare now permanently covers virtual supervision for certain services and has removed frequency limits on virtual visits for patients in nursing facilities.
Furthermore, 2026 introduces coverage for digital mental health treatment devices. If your doctor prescribes a digital therapeutic (like an FDA-cleared app for ADHD or depression), Medicare may now help cover the cost. This is part of a broader push to integrate behavioral health into primary care. For more on these modern updates, see our Medicare Part B Giveback Complete Guide.
Frequently Asked Questions about 2026 Medicare Part B
What is the standard monthly Medicare Part B premium for 2026?
The standard monthly premium is $202.90. This is an increase of $17.90 from the 2025 premium of $185.00. Most people have this amount deducted directly from their Social Security checks. You can find more updates on this under our Tag/Part B Premium/.
How much is the 2026 Medicare Part B deductible?
The annual Part B deductible for 2026 is $283.00. You must pay this amount for covered outpatient services and doctor visits before Medicare begins to pay its share. This deductible resets every year on January 1st.
Does LAFPP provide Medicare Part B premium reimbursement for 2026?
Yes, for members of the Los Angeles Fire and Police Pensions (LAFPP), there is a specific reimbursement policy. If you are an eligible retiree enrolled in Medicare Part B, LAFPP may reimburse you for the standard portion of your premium. Members should check their specific benefit statements to see how the 2026 increase affects their reimbursement amount.
Conclusion
Navigating 2026 Medicare Part B can feel like a full-time job. Between premium hikes, IRMAA surcharges, and shifting deductibles, it’s easy to feel like your Social Security check is under siege. But remember, you don’t have to navigate this alone.
At We Can Help You, Inc., our mission is to provide the education you need to protect your retirement. Whether you are living in Florida, New York, Ohio, or any of our other service locations, we are here to help you maximize your benefits.
Don’t let the 2026 hike catch you off guard. Take the first step toward a more secure retirement today: Get your free Medicare Planning Guide and ensure you’re making the most of every dollar in your Social Security check.