Why Retirement Planning Experts Make All the Difference
As we look toward May 2026 planning trends, achieving your retirement goals and long-term financial peace requires more than just a savings account. Retirement planning experts are professionals who help you turn decades of savings into a reliable income — while protecting you from costly tax mistakes, Medicare missteps, and Social Security timing errors.
Here are the top types of retirement planning experts to know:
| Type of Expert | Best For | Key Credential |
|---|---|---|
| Fee-Only Fiduciary Advisor | Unbiased, conflict-free planning | NAPFA membership |
| Certified Financial Planner | Comprehensive retirement strategy | CFP® designation |
| Retirement Income Specialist | Income distribution planning | RICP designation |
| IRA/Tax Specialist | Tax-efficient withdrawal strategies | CPA/PFS or Ed Slott trained |
| Social Security & Medicare Advisor | Benefit timing and enrollment | Specialized training |
The transition into retirement isn’t just about having enough money saved. It’s about how you use it. And that’s where most people get into trouble.
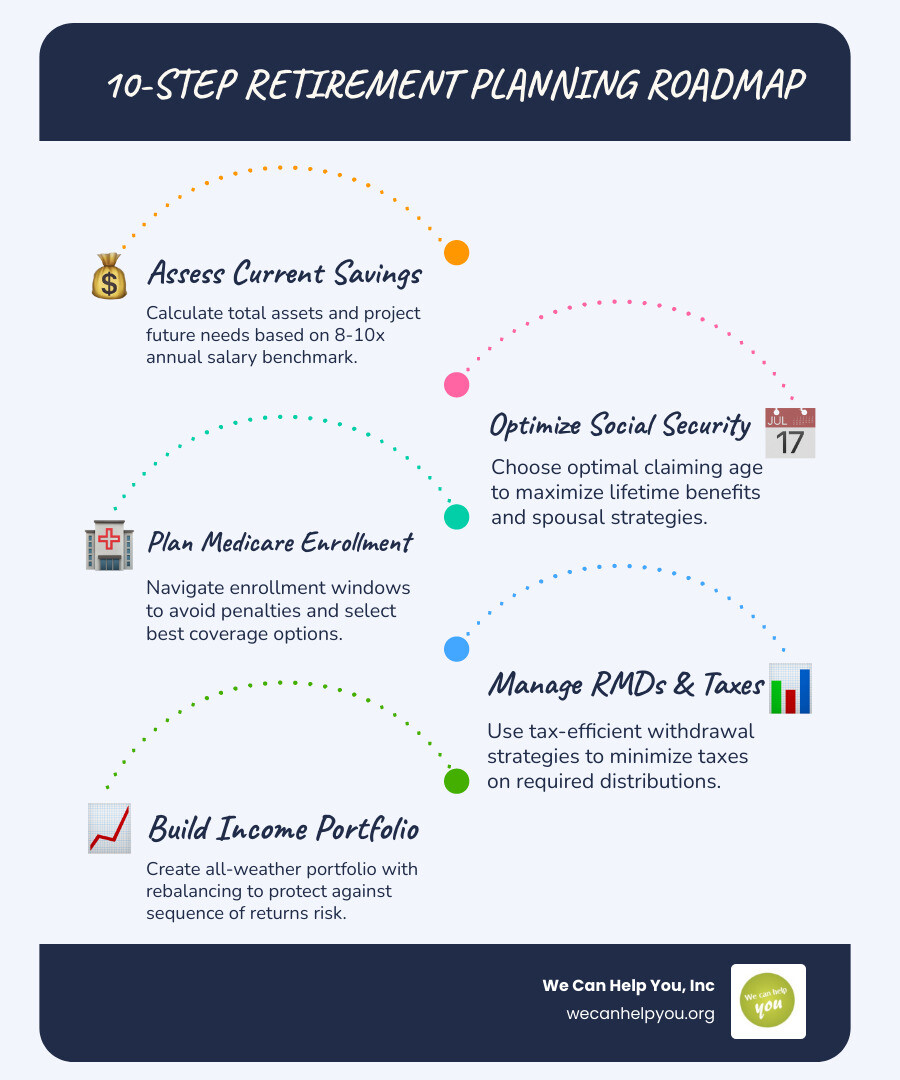
Experts recommend saving 8–10 times your annual salary before retiring and replacing 65–80% of your pre-retirement income each year. But knowing those numbers is only the start.
The real challenge? Navigating Medicare enrollment windows, Social Security claiming decisions, Required Minimum Distributions (RMDs), and rising healthcare costs — all at once, all with real financial consequences if you get them wrong.
The good news: the right expert can add serious value. Vanguard research shows that professional advisor best practices can add roughly 3% per year in overall performance — through behavioral coaching, smart rebalancing, and cost-efficient implementation.
Working with a retirement specialist isn’t a luxury. For most people approaching or entering retirement, it’s the single most important financial decision they can make.
What to Look for in Retirement Planning Experts
When you are looking for retirement planning experts, you aren’t just looking for someone who is good with numbers. You are looking for a partner who can navigate the complexities of the “living in retirement” phase, which is vastly different from the “saving for retirement” phase.
At We Can Help You, Inc., Our Mission is to empower you with the education needed to make these choices with confidence. A key part of that is knowing which credentials actually matter. You should prioritize experts who hold the CFP® professional designation, as they have met rigorous education and ethical standards.
For those specifically focused on turning assets into a paycheck, look for the RICP (Retirement Income Certified Professional) designation or FSCP (Financial Service Certified Professional) credentials. If your concerns are heavily weighted toward taxes, a CPA/PFS (Personal Financial Specialist) brings a unique blend of accounting and financial planning expertise to the table.
Prioritizing Fiduciary Standards and Ethical Guidance
The most critical quality to look for is a fiduciary duty. A fiduciary is legally and ethically bound to act in your best interest at all times. This might sound like common sense, but not all advisors operate this way. Some are “broker-dealers” who only have to meet a “suitability” standard, meaning they can recommend products that pay them a higher commission as long as the product is “suitable” for you.
To avoid this conflict of interest, we recommend seeking out fee-only advisors, such as those registered with NAPFA (National Association of Personal Financial Advisors) who adhere to strict NAPFA standards. Fee-only experts are compensated only by their clients—never by commissions from product sales. This ensures their advice is centered entirely on your goals, providing a level of transparency and professional accountability that is essential for long-term trust.
Choosing an Advisor Based on Your Asset Level
Your choice of expert often depends on the complexity of your portfolio. Many top-tier firms have specific tiers of service:
- Guided Advice: Often available for those with $100,000 to $250,000 in investable assets.
- Dedicated Advisors: Many personalized planning services require a minimum of $250,000 in household assets.
- Specialist Teams: High-net-worth individuals, often defined as those with $1M to $1.5M+ in assets, may require a dedicated team of specialists to handle complex estate, gifting, and tax-loss harvesting strategies.
Matching the expert’s specialty to your portfolio complexity ensures you aren’t paying for services you don’t need, or worse, missing out on advanced strategies that could save you six figures in the long run.
The Critical Role of the Retirement ‘Red Zone’
In professional planning, we often talk about the “Red Zone.” This is the 10-year window consisting of the five years immediately before you retire and the five years immediately after. This phase is the most critical period for your financial success. Decisions made here regarding Social Security, Medicare, and withdrawal sequences will echo for the rest of your life.
To help you navigate this, we’ve developed Your Retirement Roadmap To Financial Freedom, which highlights the specific milestones you need to hit during this transition.
Why Specialized Retirement Planning Experts Focus on the Red Zone
During the Red Zone, the goal shifts from “accumulation” (growing your money) to “distribution” (spending it wisely). Experts focus on:
- Sequence of Returns Risk: A market crash right as you start taking withdrawals can devastate a portfolio. Experts use “income protection” strategies to ensure your basic needs are met regardless of what the stock market does.
- Timing Strategies: Coordinating the exact month you stop working with the start of your benefits to avoid gaps in healthcare coverage or unexpected tax spikes.
- Lifestyle Adjustments: Helping you transition from a “saver” mindset to a “spender” mindset without the anxiety of “running out of money.”
Protecting Your Income from Market Volatility
A “worry-free” retirement is built on what many experts call an “All-Weather” portfolio. This approach is designed to generate dependable income through changing market cycles.
One of the biggest values an advisor provides is behavioral coaching. Vanguard quantifies this specific service as adding about 1.50% to your annual performance. Why? Because an expert keeps you from making emotional decisions—like selling everything during a market dip. Combined with disciplined rebalancing and cost-effective implementation, professional management can provide a total performance boost of approximately 3% per year.
Advanced Strategies for Tax and Healthcare Optimization
As you enter your 60s and 70s, the “whack-a-mole” game of legislative changes, like the Secure 2.0 Act, becomes a major factor. Retirement planning experts like Ed Slott emphasize that without proactive planning, your IRA can quickly become a “windfall for Uncle Sam.”
How Retirement Planning Experts Navigate Tax and Medicare Complexity
Tax-bracket management is an art form. Experts look at your “net-of-tax” wealth, not just the balance on your statement. This involves:
- Tax-Deferred vs. Tax-Free: Deciding when to pull from traditional IRAs versus Roth accounts to minimize the lifetime tax bill.
- RMD Management: Planning for Required Minimum Distributions so they don’t push you into a higher tax bracket or trigger higher Medicare premiums (IRMAA).
- Medicare Integration: Choosing between Original Medicare and Medicare Advantage requires a deep dive into your health needs and budget. We provide a Medicare Planning Complete Guide to help you understand these options.
- Enrollment Windows: Missing a Medicare Part B window can lead to lifelong late-enrollment penalties. If you feel overwhelmed, remember: Dont Go It Alone Where To Get Help With Medicare Today.
Maximizing Social Security and Legacy Planning
Social Security is often the bedrock of retirement income, yet many people claim it as soon as they can, potentially leaving hundreds of thousands of dollars on the table over their lifetime. Experts like Marcia Mantell point out that Social Security and Medicare are the “expert level” pillars of a plan.
Standard benchmarks suggest having 8–10 times your annual salary saved, but the timing of your Social Security claim and understanding spousal benefits can drastically change how much of that savings you actually need to touch. By optimizing your claim, you can protect your legacy and ensure your heirs receive more of your hard-earned wealth.
Essential Tools and Fee Structures for Expert Planning
Understanding how you pay for advice is just as important as the advice itself.
| Feature | Fee-Only Advisor | Commission-Based Advisor |
|---|---|---|
| Compensation | Paid only by the client | Paid by product sales/commissions |
| Fiduciary Duty | Always required | Not always required |
| Conflict of Interest | Minimal | High potential |
| Average Fee | ~0.50% average net fees | Varies (often hidden in products) |
Leveraging Technology for Income Projections
Top firms use advanced tools to give you a clear picture of your future. These include:
- Retirement Income Calculators: These estimate your monthly cash flow needs based on inflation adjustments and projected spending.
- Guaranteed Income Estimators: Used to see how products like annuities can cover your “essential” expenses.
- Healthcare Cost Estimators: Tools that project future medical expenses to ensure your plan remains solvent.
- Digital Questionnaires: Modern experts use these to capture your risk tolerance and goals in about 15–30 minutes, creating a point-in-time plan that serves as your initial roadmap.
Understanding the Value of Comprehensive Advisory Fees
While some might balk at a 0.9% total cost (which often includes both the advisor’s fee and the underlying fund expenses), the value provided is comprehensive. Experts like Randy Thurman or Joe Lucey use frameworks involving 52 essential questions to remove uncertainty. This proactive risk management, asset location strategy, and focus on wealth preservation prevents “cat food” retirement scenarios and builds the long-term confidence needed to actually enjoy your free time.
Frequently Asked Questions about Retirement Guidance
What is the difference between a fee-only and a fee-based advisor?
A fee-only advisor is paid directly by you and does not accept commissions from insurance companies or investment firms. A fee-based advisor receives fees from you but also accepts commissions from products they sell. For the highest ethical standard and least conflict of interest, fee-only is the gold standard.
How much should I have saved before consulting an expert?
While some experts work with clients at any level, many specialized firms have minimums of $250,000. However, if you are in the “Red Zone” (within 5 years of retirement), seeking education and a one-time plan is valuable regardless of your total asset count.
Why is Social Security optimization critical for my plan?
Social Security is one of the only inflation-adjusted, guaranteed-for-life income sources you have. Claiming at age 62 versus age 70 can result in a 76% difference in your monthly benefit amount. An expert helps you decide the best age to claim based on your health, other assets, and marital status.
Conclusion
Retirement should be a time of joy, not a period of constant financial stress. By working with the right retirement planning experts, you can navigate the complex maze of taxes, healthcare, and income distribution with ease.
At We Can Help You, Inc., we are dedicated to making this transition as smooth as possible for residents across the country, from Phoenix, AZ to Albany, NY, and Charlotte, NC to Chicago, IL. We offer a free Medicare Planning Guide and a free Social Security maximization report to help you start your journey on the right foot.
Don’t guess your way through your golden years. Take control of your future today by visiting our Social Security resource page and let us help you build the worry-free retirement you deserve.